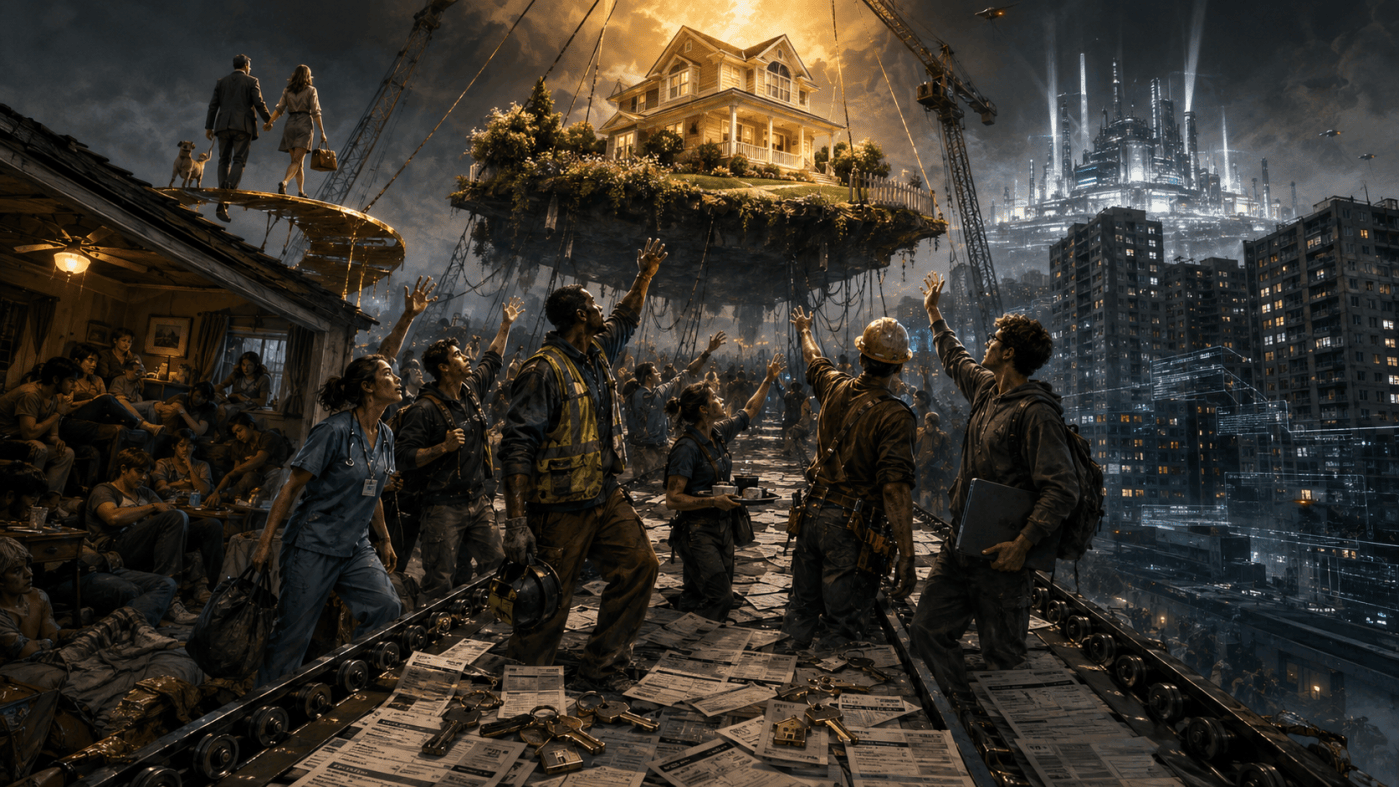
The business press calls it the “Great Postponement,” dressing the collapse of independent working-class life in the harmless language of delayed milestones. Beneath the euphemism, employed young adults are trapped between rising rents, mortgage exclusion, weakened labor power, inherited inequality and a property system still structured by racial dispossession. The state can plan, subsidize and coordinate strategic industry when monopoly capital demands it, yet leaves workers to secure housing through debt, family wealth and algorithmically managed scarcity. The answer is not another lesson in budgeting poverty, but tenant unions, workplace organization and collective struggle wherever landlords extract rent and corporations collect public money.
Prince Kapone | Weaponized Information | July 31, 2026
The American Dream Has Been Placed on Layaway
In “Hard Work Isn’t Enough to Achieve the American Dream Anymore, Says Wharton Professor. Welcome to the ‘Great Postponement’”, published by Fortune and republished through Yahoo Finance on July 29, 2026, Eleanor Pringle delivers a remarkable confession from the house organ of respectable capital: millions of young workers are doing what they were told, holding down jobs and trying to save, yet still cannot afford to leave their parents’ homes, purchase a house, marry or raise a family. The promise remains on display in the shop window. The doors, however, have been locked.
Pringle, an economics and personal-finance reporter for Fortune, calls this condition the “Great Postponement.” The phrase performs the article’s central ideological work. It takes the erosion of independent adulthood and turns it into a scheduling inconvenience. Homeownership has not moved beyond the reach of millions; it has merely been delayed. Marriage and family formation have not been placed under growing material pressure; young people are simply reaching their milestones later. The social order repossesses adulthood, then hands the victims a revised calendar.
The story is constructed through a carefully controlled hierarchy of authority. A Wharton professor interprets the crisis. Realtors measure it. Mortgage institutions price it. Housing-industry experts offer policy solutions. The young workers living at home appear mainly as numbers. They are counted, classified and discussed, but never allowed to explain the conditions governing their own lives. Their employment is acknowledged because the fact that most of them hold jobs makes the old sermon about laziness impossible to sustain.
The article also stacks the economic deck. Mortgage rates, housing supply, personal saving and parental assistance receive attention, while landlord power, racialized property accumulation, weakened labor organization, corporate ownership and algorithmic rent-setting remain outside the frame. Even its use of the Realtors’ affordability index contradicts the article’s own explanation of how the measure works, yet the statistical confusion passes without examination.
Finally, the recently enacted ROAD to Housing Act is offered as a possible route back toward the dream, but its premises are left untouched. The article does not ask whose interests its incentives serve, what forms of ownership it preserves or whether expanding private construction and credit can overcome the conditions already keeping employed workers from secure housing. This restraint fits Fortune’s declared mission to make business better. The question is never whether the housing system serves working people. The question is how that system might operate more smoothly.
The ideological function is therefore plain. The business press can admit that hard work no longer guarantees a home, independence or family stability, provided the failure is presented as temporary delay rather than social rupture. The dream survives by being pushed further into the future, where it can continue disciplining workers long after it has stopped delivering what it promised.
A Paycheck That Cannot Clear the Front Door
A record 25.2 million adults under 35 lived with their parents in 2025, equal to 33 percent of the age group. Had the co-residence rates of the early 2000s continued, nearly 4.9 million fewer young adults would have been living at home. Among adults aged 25 to 34 in parental homes, seven in ten were employed. The same retreat from independent adulthood appears across the longer historical record. In 1975, 45 percent of adults aged 25 to 34 had moved away from their parents, entered the labor force, married and had children. By 2024, fewer than one-quarter had reached all four milestones.
Rent absorbs an expanding share of household income before ownership even enters the picture. In 2024, 22.7 million renter households spent more than 30 percent of their income on rent and utilities, representing 49 percent of all renters. Of these, 12.1 million paid more than half their income toward housing. Among renters earning less than $30,000, 83 percent were cost burdened and 66 percent were severely burdened. After housing expenses, 13 million renter households in that income range had a median of only $210 per month left for every other necessity.
Ownership is divided sharply by income. In 2024, 35 percent of adults with family incomes below $50,000 owned their homes, compared with 85 percent of those earning at least $100,000. Among adults under 60, the ownership rate for the higher-income group was more than three times that of the lower-income group. Recent movers with mortgages paid a median of $2,020 per month, compared with $1,500 among mortgaged homeowners overall.
The down payment and credit system adds another division. In 2025, excessive debt-to-income ratios were cited in approximately 43 percent of denied home-purchase applications, while more than 30 percent of successful buyers supplied down payments of at least 20 percent. White and Asian buyers were the groups most likely to put down that amount and were also more likely to receive financial support from relatives. A Federal Reserve research model estimated that parental transfers account for 27 percent of the homeownership rate among young households and for one-fifth of the Black-white homeownership gap among young adults.
These present divisions stand on a documented history of unequal access to property. Federal housing agencies, lenders and real-estate institutions used redlining and racially restrictive underwriting to deny mortgage credit to Black communities. In 2024, homeownership stood at 71 percent among white adults, 47 percent among Black adults and 50 percent among Hispanic adults. The 2025 mortgage data continued the disparity at the point of application: Black applicants faced an 18.2 percent denial rate, compared with 6.9 percent for white applicants.
The affordability index used in the article also requires correction. The National Association of Realtors defines a score of 100 as the point at which a median-income family has exactly enough income to qualify for a mortgage on a median-priced home under its assumptions. A score above 100 indicates more than the required qualifying income. The May 2026 score of 105.1 therefore placed the median family slightly above the index threshold, not below it. The calculation assumes a 20 percent down payment, making the result dependent on a household already possessing substantial cash or family assistance.
The national union membership rate stood at 10 percent in 2025, down from 20.1 percent in 1983, while private-sector membership was only 5.9 percent. Union members earned median weekly wages of $1,404, compared with $1,174 among nonunion workers. The Bureau of Labor Statistics cautions that occupational, industrial, age and geographic differences also contribute to that earnings gap.
Rental administration has also been centralized through common data systems. In July 2026, the Justice Department filed a proposed settlement against Willow Bridge after earlier proposed settlements involving RealPage and other major landlords. The federal complaint alleged that competing landlords shared competitively sensitive rental data and used RealPage algorithms to generate pricing recommendations with rules that aligned rents. The proposed decree would prohibit the use of competitors’ sensitive data in pricing algorithms, restrict information sharing and require monitoring of certain third-party pricing systems.
Federal housing and industrial policy operate through markedly different instruments. The 21st Century ROAD to Housing Act became law on July 11, 2026, reducing regulatory barriers, changing HUD programs, expanding community-bank lending and restricting some institutional purchases of residential property. Its sponsors emphasized that the law includes no new federal spending and relies heavily on streamlined construction, private investment and credit mechanisms. CHIPS for America, by contrast, directs $39 billion toward semiconductor manufacturing incentives and $11 billion toward research and development, using direct public funding to expand facilities, equipment and the domestic technology base.
The Worker Is Employed, but Adulthood Has Been Foreclosed
The “Great Postponement” is not a delayed version of the American Dream. It is the breakdown of the material bargain that once connected employment to an independent life. Millions of young adults are working, yet remain unable to leave their parents’ homes, establish households or purchase property. The economy has not excluded them from labor. It has absorbed their labor while placing the ordinary conditions of adulthood beyond their reach.
This is a crisis of social reproduction. A worker must secure shelter, food, transportation and the other necessities required to return to work each day and raise the next generation. But when rent consumes such a large share of income that almost nothing remains, housing stops functioning as the foundation of life and becomes an extraction machine standing between the worker and every other need. The problem is not that young workers have forgotten how to save. The arithmetic has been arranged against them.
Ownership deepens the division. Those entering the housing market do not arrive with wages alone. Many arrive with parental transfers, family equity and the accumulated advantages of earlier property ownership. Others arrive carrying debt, high rent and no inheritance large enough to clear the down payment. Two workers may earn similar wages and perform similar labor, yet one crosses the threshold into ownership because previous generations already possessed property. The other continues paying rent while being told that the difference is discipline, patience or better planning.
Here class inheritance dresses itself as individual merit. Property accumulated in one generation becomes the entrance fee for the next. The worker without family wealth must purchase access to housing through decades of interest payments, if access is granted at all. The worker with family assistance begins from a different starting line, then receives the social title of homeowner as though the market had measured personal worth rather than inherited advantage.
This inequality remains inseparable from the racial history of American property. Redlining and discriminatory lending did not merely prevent Black families from buying particular houses in particular neighborhoods. They interrupted the accumulation and transfer of property across generations. The resulting gaps in homeownership and mortgage access continue to determine who can assist their children, who enters the market with collateral and who remains exposed to rent. The so-called American Dream was never distributed universally. It was organized through a racialized ladder of incorporation, exclusion and inherited security.
Now even that limited settlement is contracting. The ruling class continues to demand educated, credentialed and disciplined workers, but refuses to guarantee that employment will provide stable housing. The worker must remain available to the labor market while adapting personal life to the demands of rent, debt and property prices. Independence becomes conditional. Marriage becomes a cost calculation. Children become another line in the household budget. Adulthood is not abolished in law; it is rationed through income and family wealth.
The decline of organized labor leaves workers confronting this system from a weakened position. Landlords, banks and property companies operate through institutions capable of setting terms across thousands of households. Workers usually enter the housing market as isolated applicants and tenants. Property is organized. Finance is organized. Rent-setting is organized. The tenant is offered a customer-service number.
That imbalance now extends into the digital administration of shelter. Rental data can be pooled, processed and converted into pricing recommendations across large property portfolios. The tenant’s need for a home becomes an input in a revenue system. Scarcity is measured, compared and monetized. This is the technofascist edge of the housing crisis: not a machine replacing the landlord, but technology strengthening the landlord’s command over the tenant.
The algorithm does not need to understand hunger, family stress or the fear of eviction. It only needs to estimate what the market can extract. Human need enters the system as data. Rent leaves it as a recommendation. The technological language makes the process appear neutral, as though the increase emerged from mathematics rather than ownership. But the software does not own the building. It serves those who do.
The contrast between housing policy and semiconductor policy reveals that the state has not lost the capacity to plan. When strategic technology and domestic manufacturing are at stake, billions can be directed through public incentives, research programs and coordinated industrial policy. Housing receives streamlined regulation, expanded credit and another invitation for private investment. One sector is treated as too important to leave entirely to the market. The reproduction of the workers expected to operate that economy is left within the market’s grip.
This is selective reindustrialization without broad social reincorporation. The state is preparing production for strategic competition while refusing to rebuild the social conditions that would allow the working class as a whole to live securely. Workers may be needed in new factories and technology corridors, but their housing remains subordinate to private profit, inherited wealth and debt qualification. Capital plans production collectively and leaves survival to the household.
That is the substance of domestic labor recalibration. The emerging order does not promise that greater productivity will produce universal stability. It selectively rewards workers required by strategic industries while disciplining the wider population through rent, debt, weakened unions and dependence on family resources. The old promise was that labor would earn a place inside the system. The new demand is that workers continue laboring even after the system has withdrawn the place.
The business press calls this postponement because dispossession sounds impolite. But a generation cannot indefinitely postpone housing, family and independence without transforming society itself. An economy capable of directing public resources toward advanced industry while leaving employed workers unable to secure a home is not suffering from a lack of capacity. It is demonstrating its priorities. The American Dream has not merely moved further down the road. The road is being dismantled beneath the workers while capital constructs a private express lane for itself.
Organize the Building, Confront the Landlord, Follow the Public Money
The housing crisis will not be solved by teaching workers to budget more carefully inside an economy designed to empty their pockets. Power must be built where rent is collected, where evictions are enforced and where public money is transferred to private industry. Tenants have to stop meeting organized property as isolated households.
The Autonomous Tenants Union Network provides a working model. Its affiliated unions are tenant-led, financed through member dues and organized independently of governments, professional nonprofits and major foundations. Its organizing library contains practical materials for forming tenant associations, canvassing buildings, preparing collective demands, supporting tenants in court and planning escalation. The immediate task is to identify the common landlord, speak directly with neighbors, build a representative committee and unite the building around demands that no tenant could enforce alone.
That organization must extend beyond a single address. Corporate owners and property-management companies control portfolios, not isolated apartments. Tenants should trace ownership records, management firms, rent increases, junk fees, repair failures, eviction filings and the use of shared pricing systems across every connected property. The member-run and dues-funded Puget Sound Tenants Union has already put this method into practice. Its Ban RUBS campaign combines tenant surveys, building communication groups, petitions, public meetings and printable materials against landlord-controlled utility charges.
Social media should feed this structure rather than substitute for it. Posts must direct tenants toward meetings, building surveys, secure message groups, petition deliveries, phone zaps, court support and picket lines. A large following may spread the story. Only organized tenants can impose a cost on the landlord.
Escalation should grow from the strength actually built. Collective demand letters, public deliveries, coordinated complaints, demonstrations and economic pressure can follow once tenants have established majority support. Rent withholding carries serious eviction and debt risks and should never be promoted as an individual gesture. The available tenant-union guides on court support, direct action and eviction defense should be studied before any confrontation that places housing at risk.
The struggle must also follow the billions flowing into strategic industry. The Communications Workers of America is sustained through a formal membership-dues structure, and CWA-backed organizing around semiconductor subsidies has demanded labor protections, community-benefit agreements, family-supporting wages and public accountability from corporations receiving CHIPS funding. Workers and residents should map every grant, tax exemption, public loan and infrastructure commitment, then demand union neutrality, affordable housing, transportation, childcare and environmental protections before subsidies are released.
The tactical sequence is clear: map the landlord, organize the building, connect the portfolio, document the extraction, deliver common demands and escalate together. Then connect tenant power to workplace organization and the struggle over public investment. Housing will not become secure because landlords discover compassion. It will become secure when working people build enough collective power to make refusal more costly than concession.
 Weaponized Information

Leave a comment